For landlords and property investors, the annual Budget often brings uncertainty. Speculation around property taxation can influence investment decisions, particularly for those looking to build portfolios, generate retirement income or invest from overseas.
The 2026 Budget is no exception. While the announced increase in income tax on rental earnings for personally owned properties has attracted attention, several other anticipated changes have not materialised.
According to Dr. Tariq, the overall outcome is more positive than many investors may initially believe.
"The 2% tax change on personal owners is negative. But overall, in my view, it is still good news for property investors."
 Dr. TariqFounder of Find UK Property
Understanding the implications of these changes, and structuring property investments appropriately, could make an important difference to long-term returns.
1.Rental income tax: what is changing?
One of the most significant announcements for landlords is the planned 2 percentage point increase in income tax on rental profits from April 2027 for properties held in personal ownership.
The personal allowance remains unchanged at £12,570, meaning eligible individuals with taxable income below this threshold may have no income tax liability.
For investors with other sources of income, however, the increase will make the tax efficiency of their property ownership structure an increasingly important consideration.
There may still be advantages for couples where one partner has little or no taxable income, or certain overseas investors who qualify for the UK personal allowance.
For example, where ownership and tax circumstances allow, a couple could potentially benefit from combined personal allowances of more than £25,000 annually.
However, eligibility, ownership arrangements and individual tax circumstances must be considered carefully.
2.Could limited company ownership become more attractive?
One of the key implications of the Budget is the potential shift towards purchasing investment properties through limited companies.
While personally owned rental income faces increased taxation, the Budget has not introduced equivalent changes to corporation tax.
The existing 19% corporation tax rate for companies with qualifying profits of up to £50,000 remains an attractive consideration for some investors, although higher rates and other tax rules apply depending on circumstances.
Dr. Tariq explains:
"It now shifts the balance towards company ownership of property for UK taxpayers."
This may be particularly relevant to higher-rate taxpayers planning to acquire multiple investment properties.
| Consideration | Personal ownership | Limited company |
|---|---|---|
| Tax on rental profits | Income tax, rising by 2 percentage points from April 2027 | Corporation tax; no equivalent change announced |
| Headline rate | Marginal income tax rate above the £12,570 allowance | 19% on qualifying profits up to £50,000; higher rates above |
| Building a portfolio | Profits taxed as personal income | Retained profits can potentially be reinvested in further purchases |
| May suit | Investors with little or no other taxable income | UK taxpayers planning two or more properties |
Summary of the points discussed in this article. Mortgage costs, accounting obligations, dividend taxation and exit plans also apply; seek professional advice.
For example, investors can establish a limited company and lend it the funds required to purchase a property. Rental profits are then taxed within the company, while repayment of the original shareholder loan can generally be made without creating additional taxable income, subject to the relevant rules.
Alternatively, retained profits can potentially be reinvested into further property purchases, helping investors build portfolios over time.
As Dr. Tariq observes:
"Buying with a company may now be the better option if you are already a UK taxpayer and plan to buy two or more properties."
However, company ownership is not automatically the most tax-efficient solution for everyone. Mortgage costs, accounting obligations, dividend taxation and future exit plans should all be considered before choosing an investment structure.
3.Capital gains tax, stamp duty and inheritance tax: welcome stability
Although speculation ahead of the Budget included potential increases in capital gains tax and changes to property transaction taxes, these did not feature among the changes discussed by Dr. Tariq.
| Tax | Position | Status |
|---|---|---|
| Income tax on rental profits (personal) | +2 percentage points from April 2027 | Increasing |
| Personal allowance | £12,570 | Unchanged |
| Capital gains tax (residential) | 18% and 24% | Unchanged |
| Stamp Duty Land Tax | Existing framework | Unchanged |
| Inheritance tax gifting rules | Including the seven-year rule | Unchanged |
Based on the Budget 2026 changes discussed by Dr. Tariq. Tax treatment depends on individual circumstances.
Capital gains tax
Capital gains tax is an important consideration for investors who eventually sell properties at a profit.
The existing residential property capital gains tax rates of 18% and 24% remain unchanged, according to the Budget analysis.
For investors owning several lower-cost properties, carefully planning the timing of disposals may help manage tax liabilities.
Selling properties across different tax years could allow investors to make use of available annual exemptions and, depending on their income and gains, potentially benefit from lower tax rates.
Stamp duty
Stamp Duty Land Tax is another significant upfront consideration, particularly for investors purchasing multiple properties.
With no further changes announced in the Budget, investors can continue planning acquisitions around the existing framework of property purchase taxation.
This provides a degree of stability when comparing investment opportunities and calculating upfront purchase costs.
Inheritance tax
Inheritance tax remains a major consideration for investors looking to create long-term family wealth.
The Budget has not introduced changes to the inheritance tax gifting rules discussed by Dr. Tariq, including the commonly referenced seven-year rule.
For investors planning to build larger property portfolios, family investment companies may provide an additional option for managing how future growth is passed between generations.
Under certain structures, parents may retain control over company decisions while allocating future growth rights to their children.
Such arrangements require specialist professional advice, but they demonstrate how appropriate ownership structures can form part of long-term estate planning.
The 2026 Budget raises income tax on personally held rental profits by 2 percentage points from April 2027, but leaves capital gains tax, stamp duty and inheritance tax unchanged.
4.Why affordable UK property could become even more attractive
Beyond the immediate tax implications, the Budget reinforces an important distinction between high-value residential property and affordable investment housing.
The prospect of additional taxation on expensive homes may encourage investors to look more closely at lower-cost properties that offer attractive rental yields.
Dr. Tariq believes this could support demand for affordable housing investments.
"There are many reasons to buy low cost houses for investment and this is another one."
For investors focused on income rather than luxury property ownership, lower-cost residential housing can offer several potential advantages.
5.Rental demand continues to support the UK property market
Although tax policy influences investment returns, the fundamental relationship between housing supply and demand remains one of the most important factors shaping the UK rental market.
For many households, purchasing a home remains financially challenging. Higher deposits, mortgage affordability requirements and wider living costs mean renting continues to be a necessity for a significant proportion of the population.
At the same time, the supply of rental accommodation remains constrained in many areas.
Dr. Tariq highlights this imbalance:
"Demand for rental continues to increase because house buying remains unaffordable for many."
With demand remaining strong and rental supply under pressure, there is continued potential for rental growth, particularly in locations where affordable housing is scarce.
However, landlords also face increasing responsibilities around property standards, compliance and tenant protections.
Changes introduced through the Renters' Rights Act add another important consideration for property owners.
While these developments are designed to strengthen protections for tenants, they can also increase the administrative and operational demands associated with managing rental property.
For investors seeking regular income without day-to-day involvement, this creates an important question: is there a more passive way to own UK property?
6.The biggest challenge for property investors is not necessarily tax
Tax efficiency matters, but it is only one part of a successful property investment strategy.
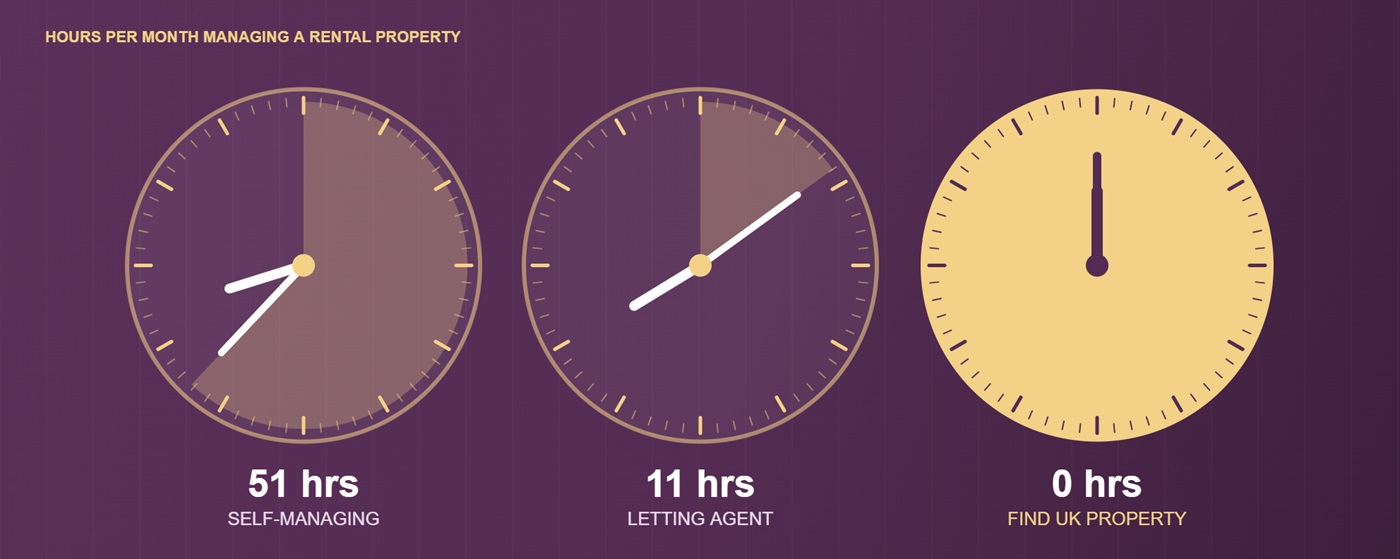
Owning rental property directly can involve significant ongoing responsibilities, from finding suitable tenants and managing repairs to dealing with maintenance costs, regulatory compliance and rental arrears.
As Dr. Tariq explains:
"The problem is that normally owning UK rental property is not 100% passive."
These responsibilities can be particularly challenging for overseas investors, retirees and individuals who want the benefits of property ownership without the additional work of being a landlord.
However, alternative arrangements can provide a more hands-off approach.
One option involves purchasing a property and leasing it to a professional property company that becomes the owner's tenant.
Under an appropriately structured agreement, the company takes responsibility for managing the property and its subtenants, including maintenance, compliance and other agreed obligations.
The property owner receives the contractually agreed rent without needing to manage the property personally.
This approach can make direct property ownership more accessible to investors who would otherwise be discouraged by the practical responsibilities involved.
7.A fully managed approach with Find UK Property
At Find UK Property, our approach is designed around making UK property investment straightforward, affordable and hands-off.
We provide fully renovated, freehold investment properties starting from under £82,000, with a contractual 7% net rental income offering.
Investors own their property outright as a freehold asset and lease it back to Find UK Property under an agreed arrangement.
We then take responsibility for managing the property, tenants, maintenance and associated costs covered by the agreement.
With over 2,500 properties under management, our model is designed for individuals seeking long-term rental income without the traditional demands of managing a buy-to-let property.
This can be particularly attractive for overseas investors, those approaching retirement and individuals looking to build a property portfolio alongside other investments.
Property ownership also provides exposure to a tangible physical asset with the potential for long-term capital appreciation, although property values and rental market conditions can fluctuate.
By combining affordable purchase prices with professional management and a clearly defined rental agreement, investors can focus on their longer-term financial objectives rather than day-to-day property management.
8.Looking ahead: a positive outlook for UK property investors
The 2026 Budget introduces some additional tax pressure for landlords holding property personally, but it has also avoided several more substantial changes that had been anticipated.
For investors prepared to consider their ownership structure carefully, opportunities remain to generate rental income and build long-term wealth through UK residential property.
The case for affordable rental housing remains closely linked to underlying housing demand, supply constraints and the enduring need for good-quality accommodation.
As Dr. Tariq concludes:
"UK property gives good income and steady long-term growth with low geopolitical investment risk."
While no investment is without risk, the combination of potentially attractive rental income, long-term capital growth and professional management continues to make UK property worth considering as part of a diversified investment strategy.
For those seeking a simpler route into the market, Find UK Property offers a fully managed solution designed to remove much of the traditional work associated with rental property ownership.
Discover affordable, fully managed UK property investment
Whether you are investing for retirement, looking to diversify your assets or seeking a reliable long-term rental income strategy, Find UK Property can help you explore the available opportunities.
Explore our investment properties and learn how our 7% net rental income offering works. Visit www.findukproperty.com or speak to our team today.
Sources and notes
Tax figures reflect the 2026 UK Budget announcements as analysed by Dr. Tariq, Founder of Find UK Property. The rental income tax increase applies from April 2027 to properties held in personal ownership.
Disclaimer: This article is provided for general information only and does not constitute financial, legal, tax or investment advice. Tax rules and investment outcomes depend on individual circumstances. Property values and rental income can change, and investors should seek independent professional advice before making decisions.