London or the North – What’s the Real Opportunity?
For years, London was seen as the obvious choice. High demand, limited supply, and a global reputation made it a magnet for investors. But that old logic no longer holds.
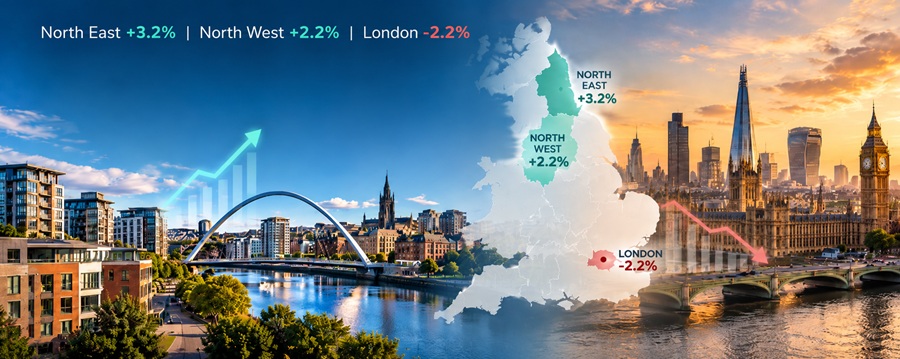
Dr. T points out that property prices in London are now four to six times higher than in the North of England. That means for the same capital you’d spend on a single flat in the capital, you could buy four or more houses in northern cities like Durham, Sunderland or Hartlepool – each generating its own rental income stream.
And that difference matters. Dr. T emphasises that when it comes to net yield per pound invested – the North comes out comfortably ahead.
The Active vs Passive Investor Divide
A key theme in the video is that your location strategy depends entirely on whether you’re an active or passive investor.
If you’re the hands-on type – fixing leaks, managing tenants, keeping up with new rental regulations – then buying close to home makes sense. You want to be in control, and London or the South East might fit that model.
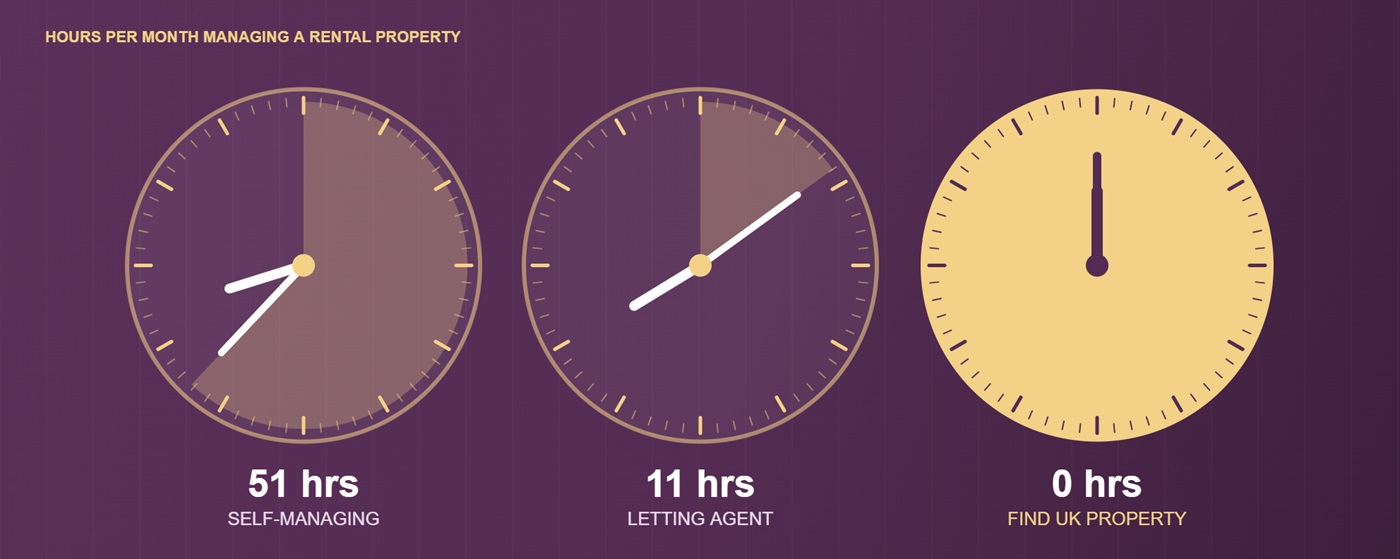
But if your goal is to own property passively, things look very different. As Dr. T explains, when you let a professional property company handle the tenancy, maintenance, and compliance, you’re no longer the acting landlord. That means you can buy wherever the returns are best – whether that’s in the North East, North West, or beyond.
It’s a subtle but powerful shift: you stop thinking like a landlord, and start thinking like an investor.
Why the North Offers a Stronger Balance
According to Dr. T, the logic behind investing in the North is both simple and data-driven.
Long-term figures show that property prices across the UK – whether in the North or South – have increased by roughly 7% a year, doubling every 12 to 13 years. So if capital growth rates are broadly similar, but entry prices are lower in the North, the percentage return is far higher.
In other words, you get the same level of growth for a fraction of the cost. Add to that the higher rental yields found in more affordable markets, and the overall return profile becomes hard to ignore.
The Direction of Future Growth
Dr. T makes another critical point: the future growth story is likely to be northern.
With billions now flowing into infrastructure, transport, energy and housing across regions like the North East, the foundations for long-term capital appreciation are being laid right now.
“Experts think that in the next 10 to 20 years, the percentage capital growth is likely to be higher in the North of England where house prices are lower,” he notes.
That view lines up with current data: the North East has recorded some of the strongest rent and price growth in the UK, driven by affordability, regeneration, and growing demand from both buyers and tenants.
Why Tax and Policy Favour the North
Dr. T also highlights an often-overlooked factor: government policy.
He warns that new tax changes introduced by the Labour government will likely impact higher-value properties most – particularly those above the £500,000 mark. That means investors buying in London could face rising ownership and acquisition costs.
By contrast, lower-cost properties in the North not only offer higher yields but also bring greater tax efficiency and lower risk exposure. For overseas investors, that combination is hard to beat.
The Bottom Line
The message from Dr. T ’s Property Prognosis episode is clear:
• London still has its place, especially for active landlords who live there.
• But for passive investors focused on reliable returns, flexibility, and long-term value – the North is the smarter play.
It’s not just about chasing postcodes anymore. It’s about following fundamentals: yield, affordability, and sustainability.
Dr. T concludes:
“If you’re a passive investor, buy where you get the best investment returns. And right now, that’s lower-cost houses in the North – not London.”
Watch the Video
For the full breakdown, including Dr. T ’s examples and investor guidance, watch the full episode of Property Prognosis:
Don’t Buy In London – now available on the Find UK Property YouTube channel.