When it comes to UK property investment, there is no shortage of opinions. From off-plan apartments to commercial units, premium homes to HMOs, investors are constantly weighing up which route delivers the best returns.
In this latest breakdown, Dr. T cuts through the noise and compares the UK’s most common property investment choices side by side. The goal is simple: identify what actually works in today’s market, especially for investors focused on long-term, passive income.
Let’s walk through the key decisions.
Residential vs Commercial: A Clear Shift
One of the biggest questions investors face is whether to enter the residential or commercial market.
Commercial property, once seen as a stable income generator, is facing structural challenges:
- Remote working has reduced demand for office space
- High street retail continues to decline under pressure from e-commerce
- Manufacturing demand has weakened
- Warehousing, after a post-Covid boom, is now oversupplied
The result is simple economics. Lower demand leads to:
- Falling prices
- Reduced rents
- Higher vacancy risk
Residential property, on the other hand, tells a very different story. The UK continues to suffer from a housing shortage. New supply is not keeping pace with household formation, which supports:
- Rising rents
- Long-term capital growth
- Consistent tenant demand
Dr. T’s conclusion here is firm: residential property offers stronger fundamentals and lower risk in the current market.
Off-Plan vs Ready Property: Certainty Wins
Off-plan developments often look attractive on the surface:
- Payment plans
- Brand new units
- Developer guarantees
But beneath that, there are several risks:
- Inflated pricing
- Leasehold structures with service charges and ground rent
- Construction delays or project failure
- Limited control over timelines
By contrast, ready-built properties offer:
- Immediate rental income
- Proven demand and pricing history
- No development risk
- Often freehold ownership with fewer ongoing costs
For investors focused on reliable returns, certainty matters more than marketing appeal. Existing properties deliver that certainty.
Cheap vs Premium: The Yield Equation
This is where the numbers become hard to ignore.
A premium property might generate higher rent in absolute terms, but the cost-to-income ratio is often weaker. Dr. T simplifies it:
- One premium property may cost four times more than a low-cost house
- It may only generate double the rent
That means:
- Lower overall yield
- Less diversification
- Higher exposure to market swings
With the same budget, an investor could instead:
- Purchase multiple lower-cost properties
- Achieve higher combined rental income
- Spread risk across multiple tenants and locations
There are trade-offs, including more management complexity. But from a purely financial perspective, lower-cost housing consistently delivers stronger returns.
Houses vs Apartments: Ownership Matters
The house vs apartment debate often comes down to one key difference: ownership structure.
Houses are typically freehold:
- Full ownership of the property and land
- No service charges
- No ground rent
Apartments are usually leasehold:
- Ongoing service charges and fees
- Restrictions from freeholders
- Limited control over the asset
This impacts both yield and growth:
- Extra costs reduce net returns
- Resale markets can be more limited
- Flexibility is restricted, especially for alternative strategies like short-term letting
While apartments can be cheaper and easier to maintain, Dr. T’s view is clear. For long-term investment performance, freehold houses come out ahead.
Small vs Large: Where the HMO Fits In
This is where things get more nuanced, and where the “HMO question” comes into play.
Large properties offer potential:
- Higher total rental income
- Opportunities to convert into HMOs or multiple units
In the right conditions, particularly in major cities and high-demand southern locations, HMOs can outperform standard lets. But there are important caveats:
- They require active management
- Licensing and compliance add complexity
- Demand varies significantly by location
In many parts of the UK, especially outside major urban centres, HMOs can struggle with:
- Lower occupancy
- Reduced tenant demand
- Higher operational effort
At the same time, broader demographic trends are shifting:
- UK households are getting smaller
- Demand for smaller homes is rising
- Energy efficiency and affordability are becoming more important
This supports strong demand for:
- Smaller terraced houses
- Single-family lets
- Lower running cost properties
For passive investors, Dr. T’s conclusion is straightforward. Smaller properties let to individual households offer a better balance of:
- Simplicity
- Stability
- Consistent yields
HMOs still have a place, but they are best suited to experienced, hands-on investors in the right locations.
The 2026 Conclusion: What Actually Works
After comparing every major route, Dr. T lands on a clear formula for today’s UK market.
The strongest investment profile is:
- Residential over commercial
- Existing properties over off-plan
- Lower-cost homes over premium
- Freehold houses over leasehold apartments
- Smaller units over larger, complex setups
Put together, this points to one standout strategy:
Affordable, existing, small freehold houses
These properties benefit from:
- High tenant demand
- Strong rental yields
- Lower risk exposure
- Better long-term growth potential
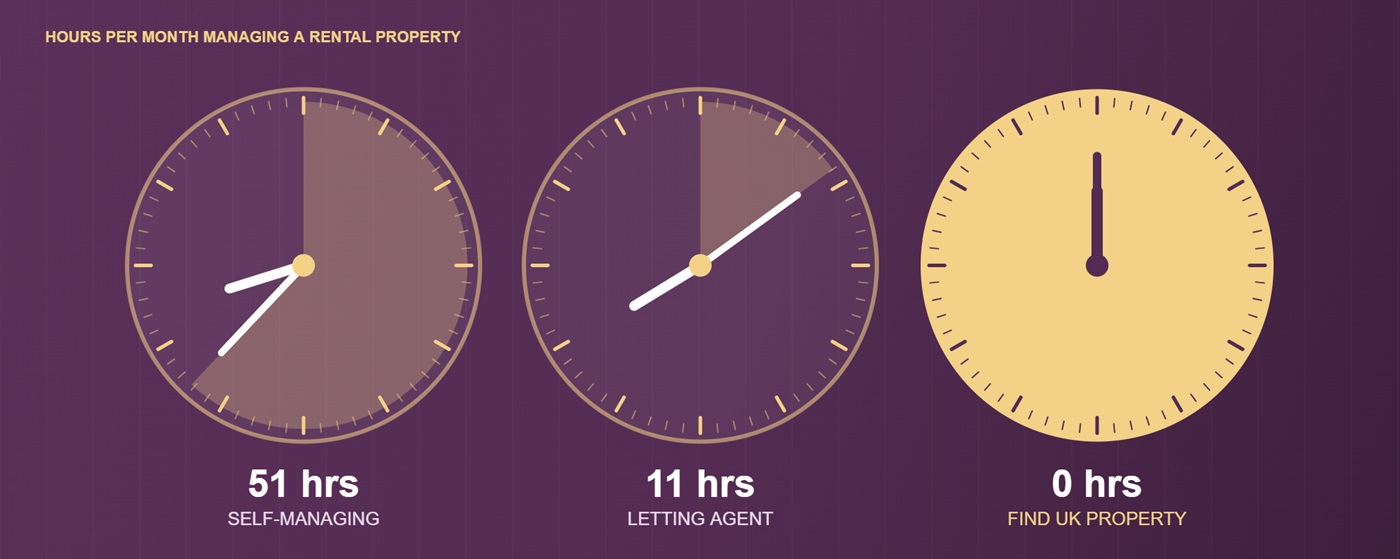
The Bigger Picture: Passive vs Active Investing
Beyond property type, there is one final consideration that matters just as much.
How involved do you want to be?
Many higher-yield strategies, including HMOs and developments, require:
- Active management
- Ongoing decision-making
- Exposure to operational issues
By contrast, simpler residential investments can be structured to deliver:
- Predictable income
- Minimal involvement
- Scalable portfolio growth
For many investors, especially those building long-term income or planning for retirement, this shift toward passive ownership is becoming increasingly important.
Final Thought
The UK property market has evolved. What worked a decade ago is not always what works today.
The data and trends now point toward simplicity, affordability, and strong underlying demand.
The real question is no longer just “what makes the most money?”
It is “what delivers consistent, reliable returns with the least risk?”
And in 2026, the answer is becoming clearer.